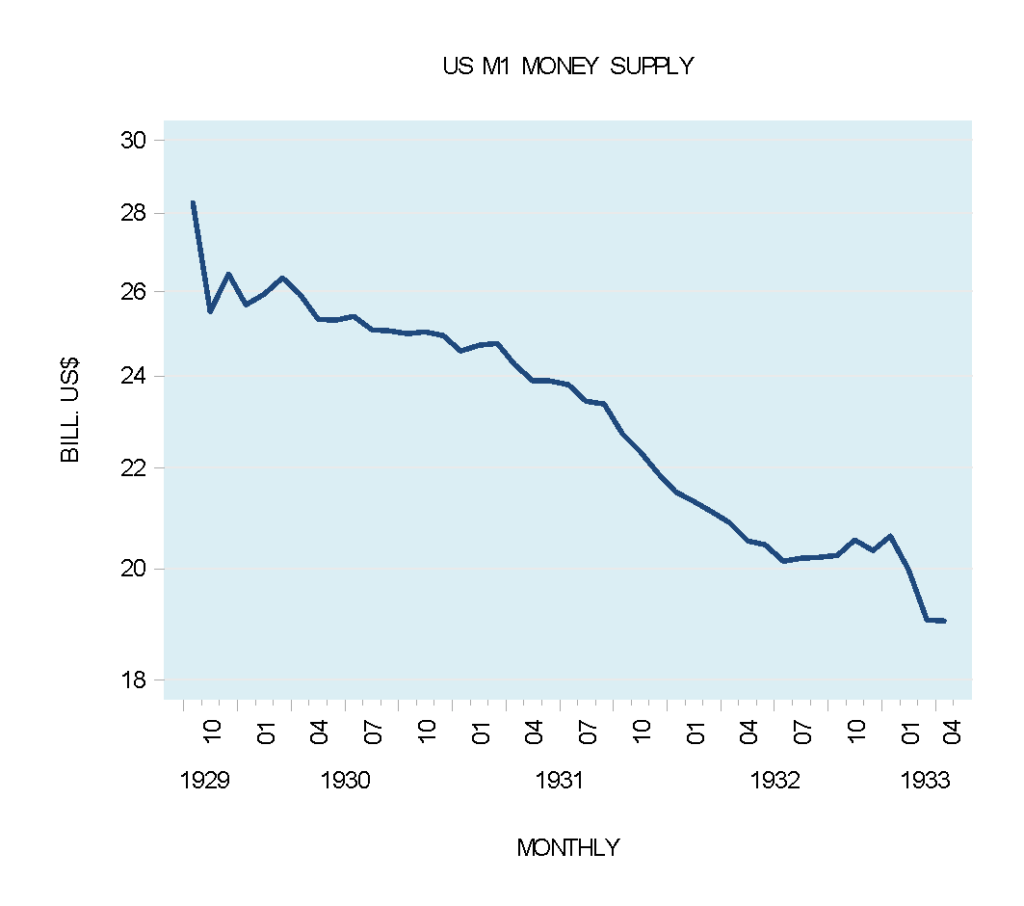
In his writings, the leader of the monetarists’ school of thinking Milton Friedman blamed the Federal Reserve for causing the Great Depression of the 1930’s. Friedman, was of the view that the US central bank failed to pump enough money into the banking system to prevent the collapse of the money supply and the economy. The money supply M1, which stood at $28.264 billion in October 1929, fell to $19.039 billion by April 1933 – a decline of almost 33%.
According to Friedman because of the collapse in the money supply, economic growth followed suit. By July 1932 year-on-year industrial production fell by over 31%. Also, year-on-year the consumer price index (CPI) plunged. By October 1932, it fell by 10.7%.
By observing a large decline in the money supply, which was followed by a large decline in economic activity and prices Friedman had concluded that the fall in the money supply was the key cause behind the Great Depression. However, observing is not explaining.
To explain what caused the Great Depression, we are of the view that one must identify the key driver of the economic growth. We hold that this is the subsistence fund.
To maintain his life and wellbeing, an individual must have at his disposal an adequate amount of consumer goods. These goods, however, are not readily available – the goods have to be extracted from the nature. Without tools at his disposal, an individual could only secure from nature very few goods for his survival.
The pool of consumer goods is the subsistence fund. The state of this fund determines the quality and the quantity of various tools that can be made. The size of this fund is determined by the production of consumer goods less its consumption. The subsistence fund sustains individuals that are employed in the various stages of production.
Note that the enhancement of the infrastructure is what makes the increase in economic growth possible, all other things being equal. The enhancement of the infrastructure in turn can take place because of the subsistence fund. Hence, anything that weakens this fund undermines the prospects for economic growth.
On this, Richard von Strigl wrote:
Let us assume that in some country production must be completely rebuilt. The only factors of production available to the population besides labourers are those factors of production provided by nature. Now, if production is to be carried out by a roundabout method, let us assume of one year’s duration, then it is self-evident that production can only begin if, in addition to these originary factors of production, a subsistence fund is available to the population which will secure their nourishment and any other needs for a period of one year……..The greater this fund, the longer is the roundabout factor of production that can be undertaken, and the greater the output will be.
We suggest that it is the expansionary monetary policies during the 1920’s that weakened the subsistence fund and set in motion the Great Depression of the 1930’s. At some periods during the 1920’s monetary injections were large. For instance, the yearly growth rate of money supply M1 increased from -12.6% in September 1921 to 11% by January 1923. Then from -0.4% in February 1924 the yearly growth rate strengthened to 9.8% by February 1925. Such large monetary pumping amounted to a large exchange of nothing for something.
The large monetary pumping resulted in the diversion of wealth from wealth generators to various nonproductive activities that emerged on the back of the expansionary monetary policy. The wealth diversion resulted in the weakening of the subsistence fund and this in turn resulted in the large economic slump.
Note, that the decline in the subsistence fund weakens the pace of economic activity. This in turn weakens bank’s credit and the credit out of “thin air” and this in turn sets the decline in the money supply. Even if the central bank were to be successful in preventing the decline in the money supply, this could not have prevented the economic depression whilst the subsistence fund is declining.
Those commentators who are of the view that by means of the monetary pumping one can prevent economic depressions, hold that this pumping is going to strengthen the aggregate demand. With the increase in the aggregate demand, it is held,the aggregate supply will follow suit. We hold that this is questionable. One has to produce something useful first before demanding things. It is not possible to increase something out of nothing.
Without an expanding subsistence fund that enables the enhancement of the infrastructure, it is not possible to increase the supply of goods and services and in turn the demand. The illusion that through the monetary pumping it is possible to keep the economy going is shattered once the subsistence fund begins to decline. Once this happens, the economy starts its downward plunge.
The most aggressive monetary pumping could not reverse the economic plunge. In fact, rather than reversing the plunge, an aggressive monetary pumping is going to further undermine the subsistence fund thereby further weakening the production structure and thus weakening the production of goods and services. Observe that money produces nothing, it is just the medium of exchange.
An examination of the historical data shows that at the onset of the economic depression the Fed was pursuing an expansionary monetary policy in its attempt to revive the economy. Monetary injections as depicted by the Fed’s holdings of US government securities increased from $165 million in October 1929 to $2,432 million by December 1932—an increase of 1,374%.
Note that when the Fed buys assets such as the government securities it pays for these assets with money out of “thin air”.
Moreover, the three-month Treasury bill rate fell from almost 1.50% on April 1931 to 0.4% by July 1931.
We suggest that the sharp decline in the money supply during 1930 to 1933 is not indicative that the Federal Reserve did not try to pump money. Instead, the decline in the money supply came because of the decline in the subsistence fund that led to the collapse in bank’s credit and credit out of “thin air” i.e. credit that is not backed by savings.
With the decline in the subsistence fund, the performance of various activities starts to deteriorate. In response to this, banks curtail their lending and their lending out of “thin air”. Observe that after growing by 2.7% year-on-year in January 1930 bank loans had fallen by a massive 29% by March 1933.
Now, when loaned money is fully backed by savings, on the day of the loan’s maturity it is returned to the bank, which in turn returns the money to the original lender. In contrast, the credit generated out of “thin air” that is returned on the maturity date to the bank results in the withdrawal of money from the economy, i.e., to a decline in the money supply.
The reason for this is that there is no original lender to whom money must be returned, since this credit was generated by the bank out of “thin air.”
Note again that contrary to popular thinking, economic depressions are the result of expansionary monetary policies that undermine the subsistence fund. Countering an economic depression by means of monetary pumping only prolongs the economic misery. What is required is to curb the money supply. This is going to arrest the depletion of the subsistence fund thereby laying the foundation for an economic recovery.
At the Conference to Honour Milton Friedman’s 90th birthday a Fed Governor Bernanke promised Friedman that the Fed is not going to make the same mistake again.
Let me end my talk by abusing slightly my status as an official representative of the Federal Reserve. I would like to say to Milton and Anna: Regarding the Great Depression. You’re right, we did it. We’re very sorry. But thanks to you, we won’t do it again.
It seems that the Fed is likely to pump money supply aggressively on any sign of emerging price deflation. Fed policy makers are so confident that Milton Friedman’s prescription is the correct way to tackle an economic depression that they are not even ready to consider the possibility that this prescription may actually make things much worse.
Conclusion
We suggest that the Great Depression of 1930’s occurred because of the Fed’s expansionary monetary policy during the 1920’s that undermined the subsistence fund. A sharp fall in the money supply during the 1930 to early 1933 was in response to the collapse of this fund. Contrary to a popular view, we hold that the Fed at the onset of the economic slump in the 1930’s made aggressive attempts to lift the money supply by expanding its balance sheet. This however failed because banks curtailed the expansion of credit out of “thin air”.